Get prequalified! Learn what your actual representative credit score is and don’t be fooled by the low-priced reports or credit services because many times these scores provided are not accurate. They also may not be the representative scores that will be used in the majority of cases for mortgage pricing and loan eligibility.
Here are some important questions you will want to know the answers to prior to putting forth the effort of applying for a loan or considering ratifying a sales contract to purchase a new home.
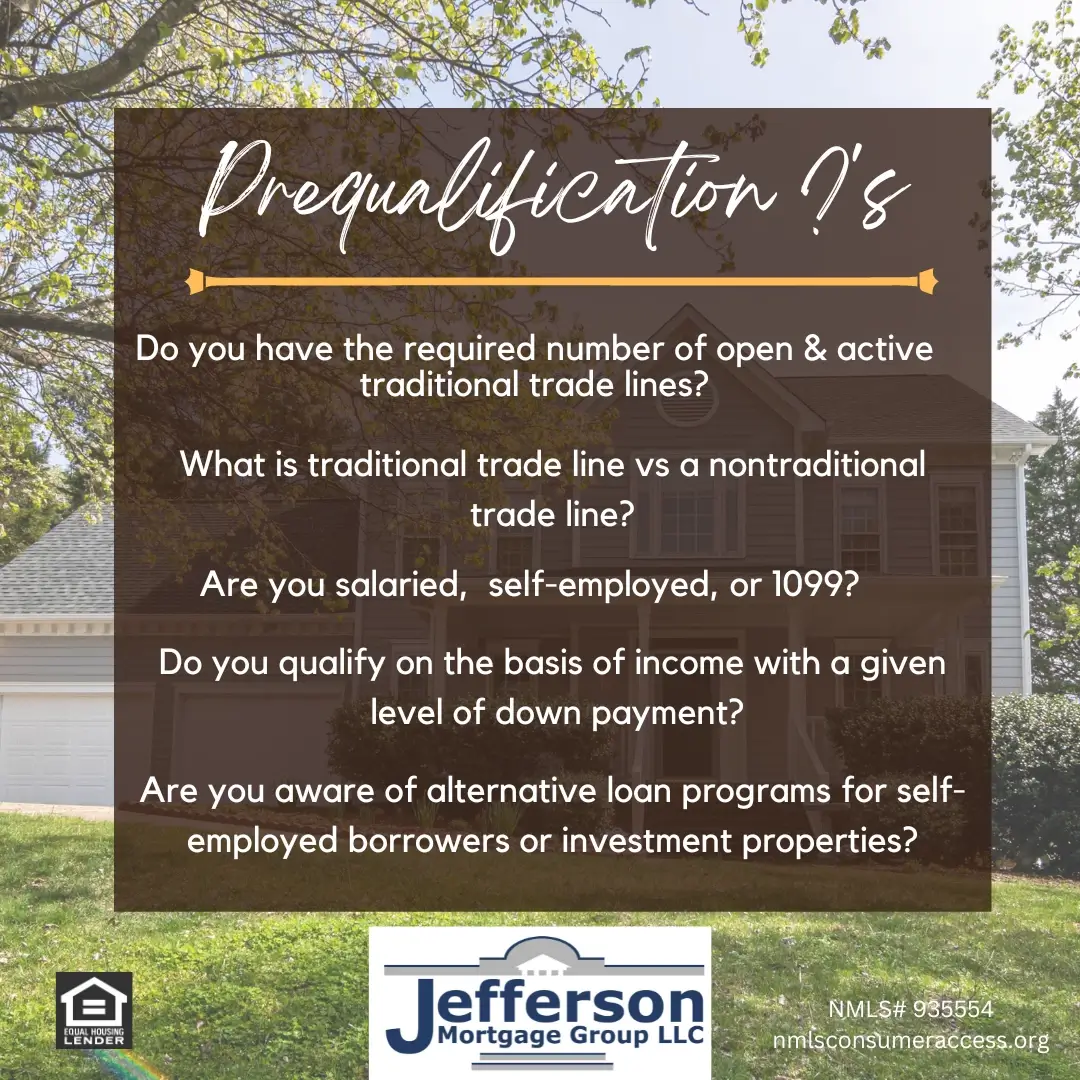
Do you have the required number of open and active traditional trade lines to qualify for a given loan program? What is a traditional trade line verses a non-traditional trade line? Can you use both for the loan program that you’re interested in? Are you salaried or self-employed, or a 1099 worker, and do you qualify on the basis of income to buy the home that you’re interested in with a given level of down payment? Are you aware of alternative loan programs that may be available for self-employed borrowers with difficult profiles or for investment properties where income qualifications may not even be required? These are some of the critical upfront questions that can be validated with investing a little bit of time with a comprehensive prequalification. If you’re a home buyer, this will often put you in the best position to have the highest probability of success when you do find the home you want in a dynamic market. It’s often a solid investment to get prequalified before you spend time and money so you know where you stand with your loan eligibility and your various loan options. No guess work just happy customers!!
George H. Omilan
President-CEO - NMLS# 873983
Jefferson Mortgage Group LLC
Programs: Traditional QM (Fannie Mae, Freddie Mac), government insured HECM Reverse Mortgages, and Non Traditional Non QM Mortgages commonly referred to as Specialized Forward Mortgages including “Alt-A Investor loans” at 80% LTV, both Full doc and No Income-No Employment (No Doc) for the investor community. Our expanded niche products also focus on the more traditional FHA & VA with Lower Score and higher Debt-to-Income Options, Fixed & Variable Jumbo loans, and Private Label Reverse mortgages for higher priced homes. We are also highly focused on specialized loans for the Self-Employed borrowers with our Bank Statement & Asset Dissipation Programs. We are committed to offering a full range of “Non-QM Loans” for expanded qualification, where the banks and large-scale lenders dare to go.